Why documentation decides hail claims
Hail claims often turn on evidence that disappears. Granules wash off, dents get painted over, cracked window screens get replaced, and a second storm muddies which damage came from which day. In North Dakota, where the severe-weather season runs roughly May through August and a single storm can drop hail across several counties, adjusters are stretched thin. The policyholder who documents early and thoroughly is in a better position whether the claim settles quickly or ends up in appraisal.
This checklist covers the home and other structures. Vehicles are insured under auto policies with their own claim process, so they are outside this list.
Right after the storm
- Note the date and time. Write down when the storm hit and how long hail fell.
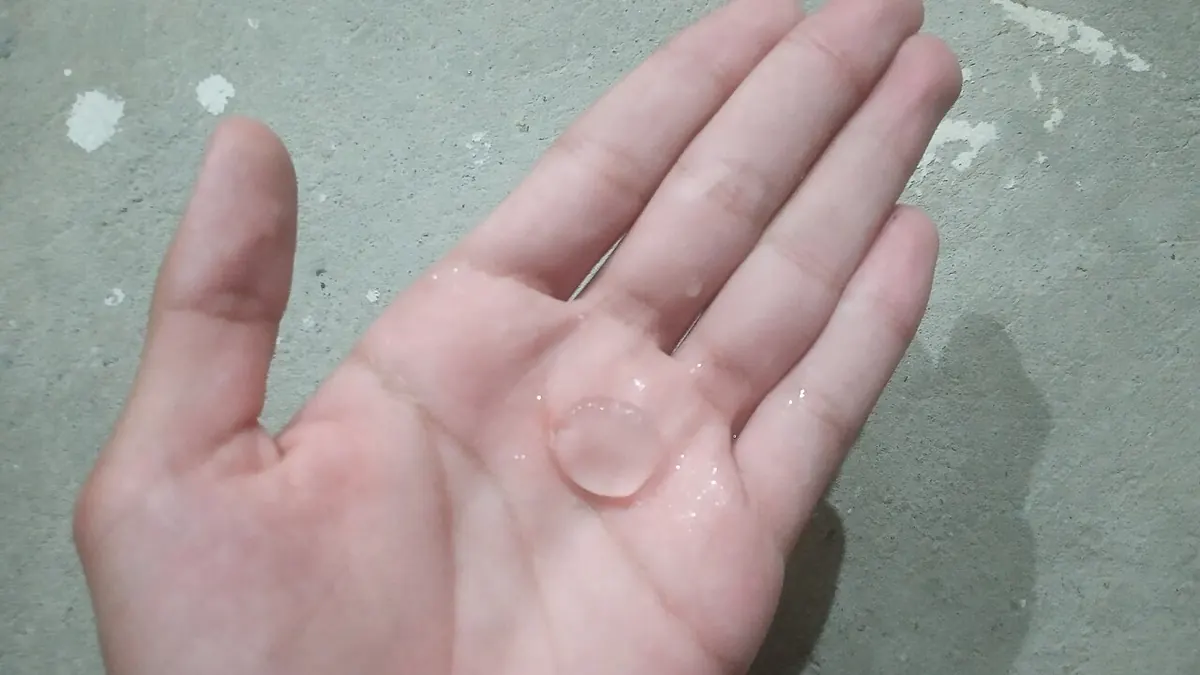
- Photograph the hail. If it is safe, photograph hailstones next to a coin or ruler before they melt.
- Save weather records. Screenshot local weather service reports or news coverage that mention hail size and location.
- Look for soft-metal hits. Dents on gutters, downspouts, mailboxes, AC fins, and grill lids are quick, visible signs of hail size and direction.
- Stop active leaks. Tarp or patch to prevent more damage, and keep receipts.
Roof
Do not climb a roof you are not equipped to walk. A contractor, appraiser, or drone can capture what you need. What matters is that the record exists.
What to capture
- Wide shots of every slope, labeled by direction (north, south, east, west).
- Close-ups of hail strikes with a chalk circle and a scale reference.
- Test-square photos, typically a 10-by-10-foot area marked with strike counts.
- Ridge caps, hip caps, and valleys, which often show damage first.
- Roof accessories: vents, pipe boots, skylights, satellite mounts, and flashing.
- Gutters and drip edge, including dents visible from the ground.
Record the roof details
Write down the shingle type and approximate age, the number of layers, the pitch, and whether ice and water shield was installed at the eaves. These details drive the estimate: steep roofs, two-layer tear-offs, and code-required underlayment all add line items that are easy to miss.
Siding
- Photograph each elevation in full, then close up on cracks, holes, and chips.
- For vinyl, note brittle fractures, which are common when hail hits in cool weather.
- For steel or aluminum siding, photograph dents with a raking light, such as early morning or late afternoon sun.
- Record the product name, color, and profile if you know them. If the siding is discontinued, that becomes a matching question later.
Windows, doors & screens
- Photograph torn or dented screens, cracked glazing, and damaged frames and wraps.
- Check aluminum window capping and storm doors for dents.
- Look at garage doors, which dent easily and are often overlooked.
Metal buildings, outbuildings & equipment
Many North Dakota properties include steel machine sheds, grain bins, or pole barns. Coverage for these depends on how they are scheduled on your policy, and farm property may be insured on a separate form. Photograph roof panels, ridge caps, wall panels, and trim, and note whether dents are only cosmetic or have broken the coating or seams. Many policies include cosmetic-damage exclusions for metal, so read your policy and record whether panels leak.
Older damage and prior claims
Insurers sometimes argue that some of the damage predates the storm. Older photos help answer that. Look through real estate listing photos, past inspection reports, or family pictures that show the roof and siding before the storm. If you had a prior hail claim, gather what was repaired and when, with invoices. A clear before-and-after record keeps the conversation on the storm that actually caused the loss.
Interior signs
Hail damage does not always leak right away. Check attics after rain for wet decking or insulation, and look for new ceiling stains in the weeks after a storm. Date-stamp those photos too.
Organizing the file
Good evidence is only useful if someone can find it. Keep one folder with:
- Photos named by date and location (e.g., “2026-07-14 south slope test square”).
- Your policy and declarations page, including any percentage wind and hail deductible.
- The claim number, adjuster’s name, and every letter and email.
- Contractor bids and the insurer’s estimate.
- Receipts for tarps, emergency repairs, and any additional living expense.
When the estimate comes back
Compare the insurer’s estimate against your photos line by line. Common gaps on hail claims include missing slopes, too few squares, no allowance for steep pitch or a second layer, missing drip edge or ice and water shield, unpriced gutters, and siding or screens left off entirely. Our guide to the claim handbook walks through how to raise those gaps with the adjuster before anything becomes formal.
If you and the insurer still disagree on the amount after a good-faith review, appraisal may be an option under your policy. North Dakota Insurance Appraiser reviews hail estimates and represents policyholders in appraisal statewide. We cannot promise a particular result, and we are not a law firm or public adjuster, but a well-documented file gives any appraiser something solid to work with.
Quick checklist
- Date, time, and hail size recorded.
- Every roof slope photographed, with test squares.
- Soft metal, gutters, and vents photographed.
- All siding elevations and windows photographed.
- Outbuildings photographed and coverage checked.
- Temporary repairs made and receipts saved.
- Claim reported promptly, claim number recorded.
- Policy, estimates, and correspondence in one folder.