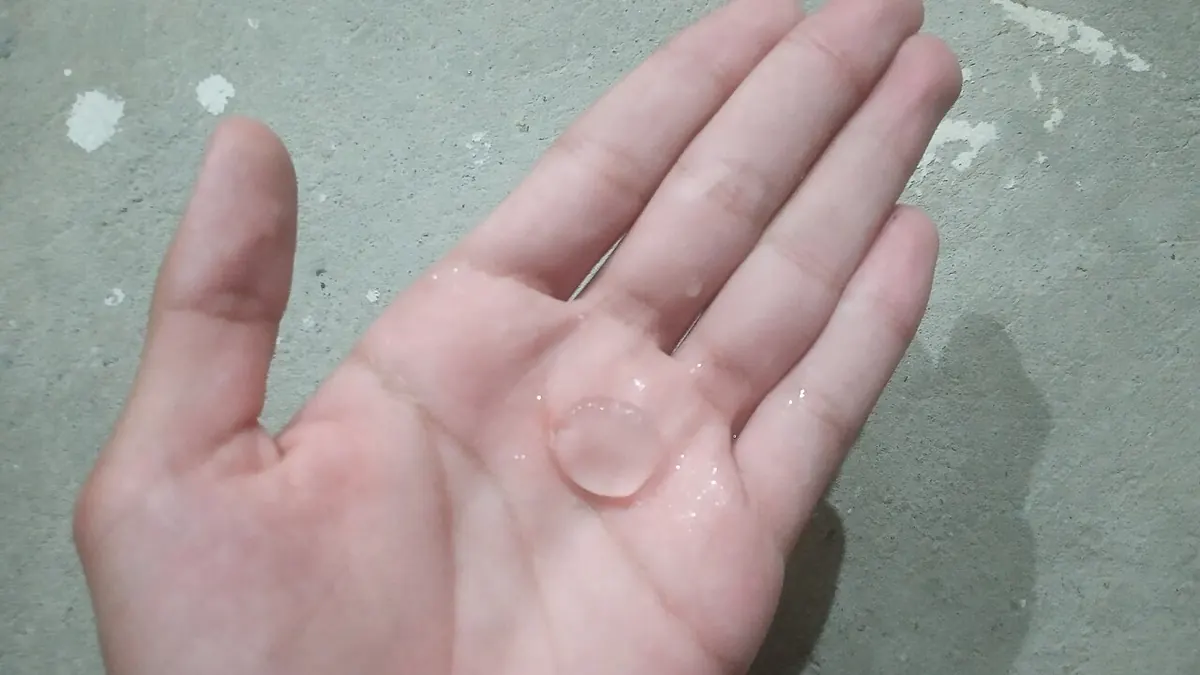
Why percentage deductibles surprise people
In hail country, some policies carry a separate wind/hail deductible calculated as a percentage of Coverage A, the dwelling limit. On a $340,000 limit (illustrative), a 1% deductible is $3,400 and a 2% deductible is $6,800 — far more than a flat $1,500 deductible for other losses.
Where to find yours
Look on the declarations page for “wind/hail,” “windstorm or hail” or a percentage next to the deductible line, then read the endorsement that defines when it applies. Some apply per occurrence; some carriers also use roof-surfacing endorsements that pay roofs on an actual-cash-value schedule.
How it affects appraisal
A deductible doesn’t change the amount of loss an appraisal panel decides, but it changes what you receive. A loss just above the deductible may not justify appraisal costs; one well above it might.
Questions about this tool
Does the percentage apply to the whole claim?
Usually the percentage is calculated from Coverage A and then applied to the wind or hail loss as a whole. Policy wording controls, so read the endorsement.
Can I change it?
Typically at renewal. A higher deductible lowers premium but raises your share of every storm loss.