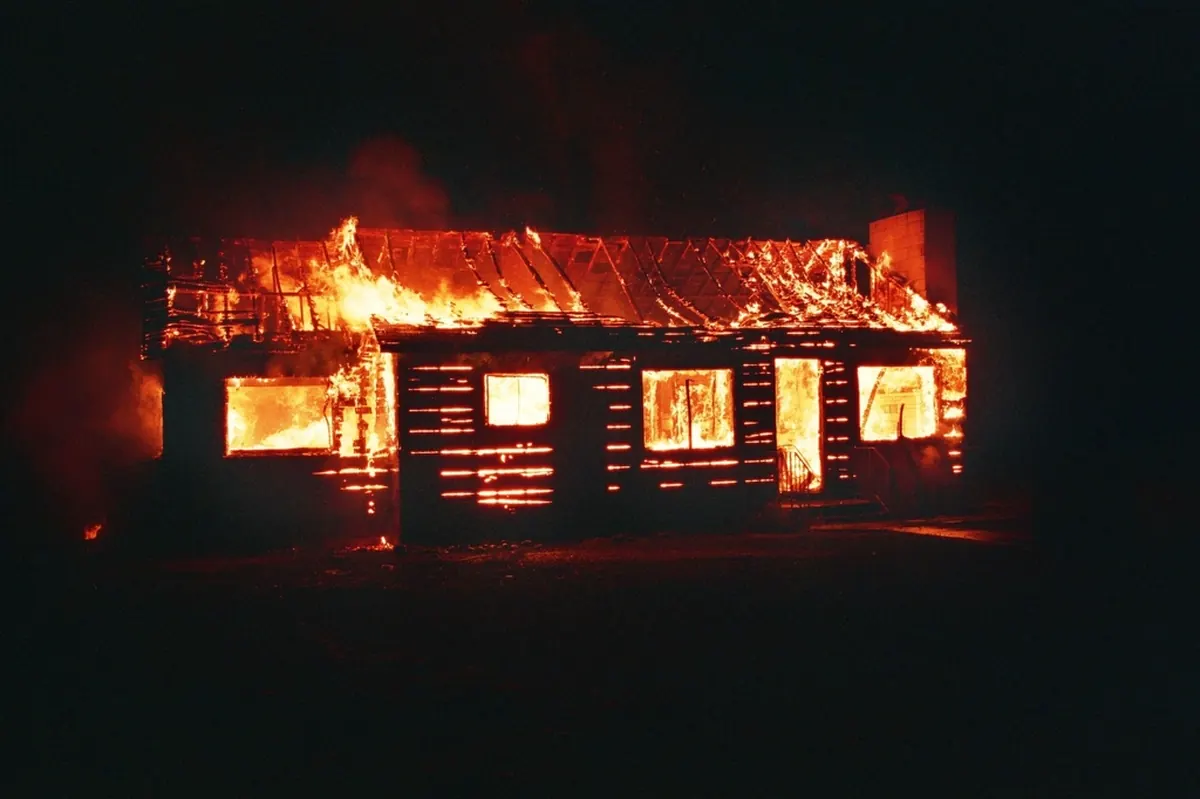
Fire losses here
House fires happen in every county, often in winter when heating equipment, chimneys, space heaters and electrical systems are working hardest. In western North Dakota, dry grassland, strong winds and drought years also bring grass fires and wildfire that can threaten farmsteads, shelterbelts, outbuildings and homes on the edge of town. Whatever the source, fire claims tend to be large, emotional and technically complex.
Where fire and smoke estimates go wrong
Clean versus replace
Smoke and soot residue settles on every surface and works into insulation, ductwork, attic framing and porous materials. Carriers often favor cleaning; sometimes that is appropriate, and sometimes residue, odor or heat damage means replacement is the only reasonable repair. We look at materials room by room and note where cleaning has been tried and failed.
Hidden heat damage
Heat can damage wiring insulation, windows, roof sheathing and framing in rooms the flames never entered. Electrical systems in particular may need inspection and partial replacement for safety and code reasons.
Water and demolition
Firefighting water soaks walls and basements, and firefighters may cut holes in roofs and walls. That damage is part of the fire loss and needs to be estimated like any water loss, including drying and in winter, protection from freezing.
Code upgrades on rebuilds
A significant fire can trigger code upgrades for electrical service, smoke and carbon monoxide detection, egress windows, insulation and more. Coverage for these depends on your ordinance or law provisions and limits.
Grass fire and wildfire exposure
When fire burns across a property rather than starting inside, damage can be patchy and easy to understate: scorched siding on one side of a shop, melted vinyl, heat-cracked windows, smoke infiltration into a house that was never touched by flame, and damaged fencing, gates and outbuildings. We walk the full property and document exposure on every structure.
How North Dakota Insurance Appraiser helps
- Review the policy, including dwelling, other structures, contents, debris removal, ordinance or law and additional living expense provisions.
- Review the fire department report and any cause-and-origin findings.
- Inspect and document smoke migration, heat damage and water damage throughout the building.
- Prepare a full estimate for mitigation, cleaning, demolition and reconstruction at current local costs, including winter conditions when they apply.
- Serve as your appraiser if appraisal is invoked.
Fire rebuilds also take time. A house that burns in December may not be fully enclosed until spring, so temporary heat, winterizing the remaining structure, security fencing and protecting salvageable materials can become real costs. We account for the timeline a contractor would actually face, not an idealized one.
Documentation that helps
- The fire department incident report
- Photos and video before cleanup and demolition began
- Board-up, mitigation and cleaning invoices
- Older photos showing finishes, built-ins and upgrades
- Any contents inventory you’ve started
Limits of appraisal
Appraisal values the loss. It does not decide coverage, cause-of-loss disputes, policy limits or claim handling concerns. North Dakota law recognizes claims against insurers for bad-faith conduct, but those are legal questions for a lawyer. We are not a law firm or a public adjuster, and we never promise an outcome.
Frequently asked questions
My house smells like smoke after cleaning. What now?
Lingering odor may mean residue remains in insulation, ducts or framing. We document it so the estimate reflects the additional work or replacement needed.
Does appraisal cover my contents?
Contents can be part of an appraisal if the policy and the dispute include them, but they need a detailed inventory with ages and replacement prices.
Can you help after a grass fire damaged outbuildings?
Yes. We inspect every affected structure, from shops and machine sheds to fences, and include them in the estimate.